Market
- Bali
- Older and more liquid.
- Lombok
- More recent.
Investing in Lombok
By Mathieu MAILLOT — 7 min read
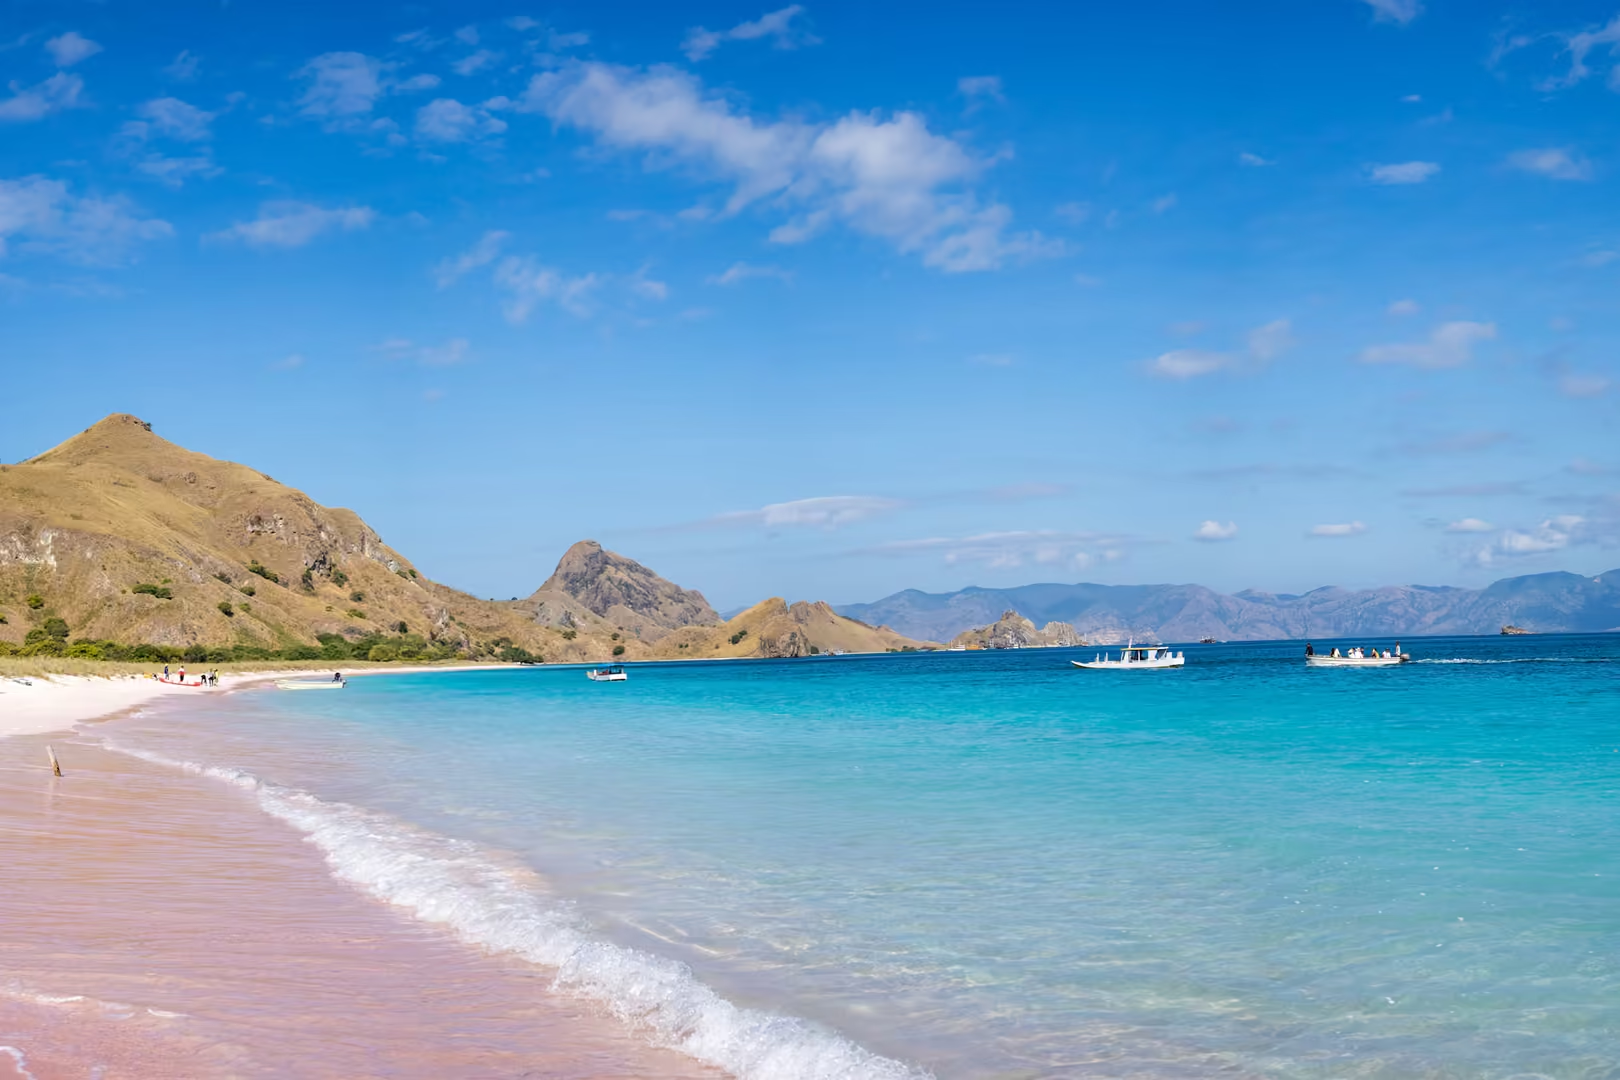
The Indonesian island of Bali has built a solid reputation among international property investors, while Lombok is attracting growing attention as a more recent alternative. Bali and Lombok remain two different markets: one is older and more liquid, the other more recent. This comparison covers the acquisition framework, tourist demand and the precautions, without a yield figure or a price.
To this day, Bali keeps a marked lead over Lombok, with an older land market, established tourist demand and developed infrastructure. BPS statistics are published at the BPS Bali website. They describe the province’s economy and tourism. They do not give a villa price or a villa yield. Lombok, for its part, is accelerating thanks to the Mandalika project, government support and growing appeal for investors looking to diversify.
Let us look at the dynamics specific to each island, the differences in pricing and the regulation particular to property investment.
Bali has long experience of buying, rental management and property development, notably in areas such as Canggu, Uluwatu and Ubud. The legal framework there still calls for careful preparation, in particular to distinguish hak milik, hak sewa and hak pakai. Lombok remains a more recent market: Kuta Lombok, Mandalika and Selong Belanak are carried by tourism projects and by sporting events. That is not a quantified forecast.
This is reflected in a gradual structuring of local agencies, improving access to finance and a greater presence of networks specialised in luxury villas or in developments for expatriates.
No price per square metre is stated here, for lack of a dated official source. Bali remains a more contested market in the established neighbourhoods. Lombok is more uneven depending on location. Mandalika concentrates a visible share of tourism projects. A capital gain is not acquired.
Bali is an older market. Lombok is a more recent market and more uneven depending on location. Neither announces growth or a capital gain. Risk depends on the project, the location, the developer, the legal conditions and the market.
Bali has an already established short-stay market, notably in Canggu, and demand linked to wellness around Ubud. That seniority guarantees neither occupancy nor a yield.
Lombok is a more recent market. Mandalika hosts events and accommodation projects. That guarantees neither demand in Kuta Lombok nor a rental result.
No quantified yield is put forward. Rental demand remains linked to tourism. Seasonality and management weigh on the result. Uluwatu, Seminyak and Canggu are established areas, without that guaranteeing occupancy.
In Lombok, demand exists for tourism products. Off-season visitor numbers, infrastructure and the quality of rental management remain variables. The result is not guaranteed.
Bali addresses a varied audience: Western families, young graduates working remotely, retired seniors, digital workers. The hotel and residential offer is adapted to that variety of profiles.
The effects of Mandalika are gradually widening the public. That is not a quantified forecast.
When comparing Bali or Lombok for a property investment, the state of the roads, airports and public services plays a key role in both the residential and the rental experience.
Let us examine the major differences on these points, while setting out the risks specific to each island.
Bali has a dense road network, several ports, a modernised international airport and effective access to private medical care. Internet connections and administrative support are reliable enough to provide a smooth experience when buying property or during the day-to-day management of a let home.
Lombok has modernised Praya airport and is rolling out urban and tourism projects, especially in Mandalika. Progress is visible, but some parts of the island remain rural and sometimes hard to reach, notably on the north-west coast or in the mountainous centre. That also weighs on delivery times and on projects far from the best-equipped areas.
Hak milik is not open to foreigners. Hak sewa lasts for the term of the contract. A company can be considered when the activity requires it. Nothing imposes a lease of 25 to 30 years. In Bali, professionals are more used to these structures. In Lombok, choosing partners calls for closer scrutiny.
Two further factors apply: demand can vary, especially in recent micro-markets, and regulation evolves. Legal monitoring remains necessary.
The choice between investing in Bali or Lombok will depend essentially on your profile, your priorities and your tolerance for risk. Bali is an older market. Lombok is more recent. Neither island is, in principle, the safer holding.
Market
Tourism
Price and value
Acquisition framework
Infrastructure
| Criterion | Bali | Lombok |
|---|---|---|
| Market | Older and more liquid. | More recent. |
| Tourism | Established demand in areas such as Canggu or Uluwatu. Occupancy is not guaranteed. | Demand for tourism products, notably around Mandalika. The result is not guaranteed. |
| Price and value | No price or yield is stated. A capital gain is not acquired. | No price or yield is stated. A capital gain is not acquired. |
| Acquisition framework | Hak milik is not open to foreigners. The term of a hak sewa is that of the contract. | The same framework. Choosing partners calls for closer scrutiny. |
| Infrastructure | A more developed network. | Praya airport has been modernised. Some areas remain less accessible. |
Before an investment in Bali or Lombok, several questions come up among French-speaking investors.
Here are the main questions on buying property in Indonesia, between a dense legal framework and the tactics of returns.
Direct access to classic full ownership remains impossible. Solutions exist through leasehold or a purchase by a local corporate structure. A rigorous check of the property, the land title and the validity of the contracts offered is required in both cases, generally with more professional support in Bali.
In the developing areas of Lombok, it is advisable to work with experienced counterparts and to watch legislative change.
Is the Balinese market at risk of saturation? Should you fear a weakening of the rental return?
Concentration of supply on certain beaches increases competition. It does not translate into a return measured here. Lombok does not, in principle, offer more opportunities.
Stay attentive to tourism cycles, to changes in regulation and to the ability to place your projects in differentiated offers, especially as 2026 approaches, when demand could see new peaks.
Reforms encouraging the modernisation of infrastructure, the welcome of international visitors and the opening of the rental sector have helped maintain Bali’s regional leadership. Lombok is currently following the same path. Comparison with Thailand or Vietnam has to take account of specific criteria such as legal security, tax transparency and the sustainability of tourism development.
By widening the view, each investor refines a strategy between use, value and diversification. Bali and Lombok do not answer the same project, and no yield is guaranteed.
We advise international investors looking in Bali and Lombok: location, budget, how to hold the asset, and which projects to consider.